The Saver’s Match: An IRS Letter You Might Actually Like

You received an IRS notice. Is it panic time? Not if it’s one of these.

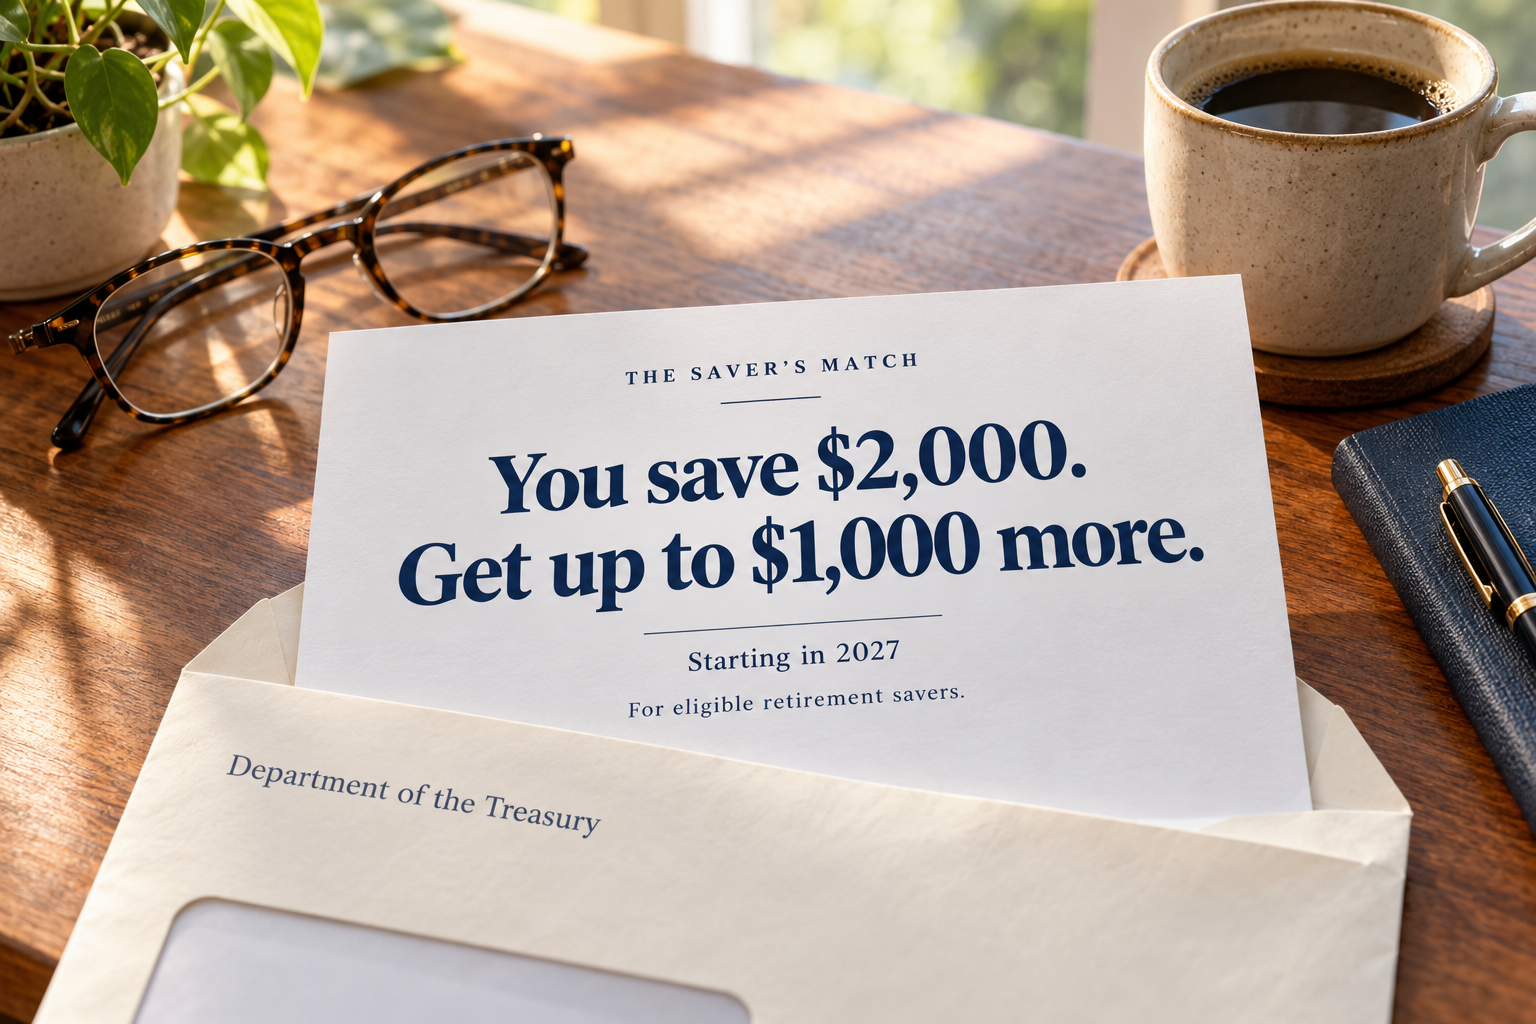
the IRS has recently been sending out Notice CP321J to let certain taxpayers know about the new Saver’s Match, a program that could add up to $1,000 per person, per year, to their retirement savings.

There are qualifications, of course. There are always qualifications. But this one deserves a look.

What happened to the Saver’s Credit?

For years, the Retirement Savings Contributions Credit, generally called the Saver’s Credit, has provided a tax break for eligible taxpayers who contribute to an IRA or a workplace retirement plan.

Depending on income and filing status, the credit is 10%, 20%, or 50% of up to $2,000 in eligible contributions per person. That makes the maximum credit $1,000 each, or $2,000 for a married couple if both spouses qualify.

Sounds pretty good. The problem is that the credit is nonrefundable.

That means it can reduce your federal income tax to zero, but it cannot take you below zero and produce an additional refund. It can increase your refund by reducing the tax against which your withholding was applied, but if you have no income tax liability to begin with, there is nothing for this credit to reduce.

So, a benefit intended to encourage people with lower incomes to save for retirement can be unusable by people whose incomes are low enough that they owe no income tax.

There may have been room for improvement.

Enter the Saver’s Match

Beginning with 2027 retirement contributions, the Saver’s Match replaces the Saver’s Credit for retirement savings. The first claims will be made on 2027 tax returns filed in 2028. The existing credit still applies for 2026.

Under the new program, the federal government will match up to 50% of the first $2,000 in qualifying contributions you make for the year. The maximum is still $1,000 per person, but the important change is that you can qualify even if you owe no federal income tax.

Generally, the money goes directly into an eligible retirement account, rather than into your checking account with your tax refund.

For example, suppose you qualify for the full match and contribute $2,000 to an IRA. The government adds $1,000 to an eligible retirement account. You have put away $3,000 for retirement at a cost to you of $2,000.

For a married couple, if each spouse makes $2,000 in qualifying contributions and each qualifies for the full match, that is $4,000 contributed by the couple and another $2,000 from the government.

The limit is per person. One spouse contributing $4,000 does not produce two $1,000 matches. Marriage allows you to share many things, but apparently not this particular contribution limit.

Incidentally, this program came from the SECURE 2.0 Act of 2022. It was not created by the One Big Beautiful Bill Act. Congress occasionally gives a tax provision several years to ripen.

Who Qualifies?

Generally, you must be at least 18 by the end of the year, not be claimed as someone else’s dependent, not be a full-time student under the applicable tax rules, and meet the U.S. tax residency requirements.

You also need qualifying retirement contributions and income within the program’s limits. For 2027:

Filing status Full 50% match at MAGI of Reduced match above that, ending at
Single or married filing separately $20,500 or less $35,500
Married filing jointly or qualifying surviving spouse $41,000 or less $71,000
Head of household $30,750 or less $53,250


At or above the ending amount, there is no match. Within the phaseout range, the match percentage gradually declines, rather than using the old credit’s 50%, 20%, and 10% brackets.

MAGI means “modified adjusted gross income,” because simply using a number already on your tax return would apparently be too convenient. For this program, certain amounts are added back, including deductible traditional IRA contributions and pretax salary deferrals to retirement plans. So, do not assume that contributing enough to bring your regular AGI below a threshold will also bring your Saver’s Match income below it.

Can I use a Roth IRA?

Yes. Contributions to either a traditional IRA or a Roth IRA can qualify, as can eligible employee contributions to workplace plans such as a 401(k).

However, there is a wrinkle: the government’s match cannot be deposited directly into a Roth IRA or a designated Roth account in a workplace plan. You would need an eligible non-Roth account to receive it.

Your Roth contribution can earn the match; the match itself needs a different home.

The match is not taxable when deposited, but amounts attributable to it generally become taxable when withdrawn. Also, retirement plans and IRA providers are not required to accept these payments, so the receiving account will need to be checked.

And now for the fine print

You do not have to contribute the full $2,000 to benefit. A qualifying $600 contribution could produce a $300 match if you qualify for the full 50% rate.

But ordinary contribution rules still apply. An IRA contribution generally requires eligible compensation, whether your own or, under the spousal IRA rules, your spouse’s. Social Security and investment income alone do not supply that compensation.

Also, certain retirement distributions can reduce the contributions eligible for a match. Putting money in and promptly taking it back out is not necessarily a shortcut to a government contribution. Early withdrawals can bring additional taxes, including special recovery rules for the match.

There is one small-payment exception to the usual retirement-account deposit: if your match is more than zero but less than $100, you may elect to receive it as a refundable income tax credit instead.

And, for completeness, the old Saver’s Credit will continue for eligible ABLE account contributions, which do not qualify for the new match. Apparently, even replacing a tax credit requires an exception.

About that IRS letter

The IRS says it sent Notice CP321J to taxpayers who claimed the Saver’s Credit on their 2025 return or whose 2025 income suggested they might qualify for the new match.

Receiving the notice does not guarantee eligibility. Your actual 2027 circumstances will determine that. Conversely, not receiving the notice does not prevent you from qualifying.

The IRS has also issued Notice 2026-48, describing how it anticipates the program will operate. Some implementation details are still being worked out, so there will be more to review before the first claims are filed.

For now, keep the opportunity in mind as you plan your 2027 retirement contributions.

And don’t immediately panic if you see a letter from the IRS in your mailbox.
One Big Beautiful Bill Act: Major Tax Provisions

The greatest thing about the passage of the One Big Beautiful Bill Act (OBBBA) is that we shouldn’t have to constantly hear about it in the news any longer. Still, you should take some time to find out what’s in it to see what it means to you, and here I will go over the major tax related items.

What is old will not be new again

Do you remember what your taxes looked like in 2016? No? Well, the good news is that you don’t need to remember.

When the Tax Cuts and Jobs Act (TCJA) was passed in 2017 there were some rather sweeping changes made to the Internal Revenue Code, including lowered tax rates, a nearly doubled standard deduction, increased child tax credits, increased estate and gift tax exemptions, and a new 20% Qualified Business Income deduction. All of which were set to expire in 2026. The primary goal of the OBBBA, then, was to prevent that expiration, and thus the passage of this law is less about being the largest tax cut in history and more about avoiding the largest tax increase. But either way you want to look at it, that expiration date is no longer hanging over our heads and those provisions have been made permanent, or at least, the automatic expiration date has been removed.

Some old favorites with slight modifications

There is a slight increase to the standard deduction for those under 65, an additional $750 for single filers and $1,500 for those filing jointly. As for those 65 or older, an extra $6,000 deduction will be added to your standard deduction, but only if your modified gross income is under $75,000 if single, $150,000 if joint, with phase outs above that. And this extra $6,000 deduction is set to expire in 2029.

The previously increased Child Tax Credit wasn’t just made permanent, it was increased from $2,000 to $2,200.

The Qualified Business Income deduction was made permanent, and remains at 20%, but the phase out of the deduction for a specified service trade or business was increased by 50%, to $75,000 or $150,000 for joint filers, thereby helping out those struggling attorneys and accountants and whatnot.

And for those that itemize, but were limited by the TCJA to only $10,000 in deductions for state and local taxes (The “SALT” deductions you may have heard about), you can now deduct up to $40,000 for 2025. This limit goes up by 1% every year, but then it reverts back to $10,000 in 2030.

And now for something completely different

No tax on tips! Up to a $25,000 deduction, if your adjusted gross income is under $150,000, or $300,000 on a joint return. And only on “qualified tips” which are defined to include only tips where such tips are customarily and regularly received. So, hospitality, yes. Doctors and lawyers, no. Oh, and this only runs through 2028.

No tax on overtime! Up to a $12,500 deduction, if your adjusted gross income is under $150,000, $300,000 for a joint return. And yes, it’s only through 2028. I’m sensing a pattern…

A deduction for car loan interest. Up to a $10,000 deduction, for those with modified adjusted gross income under $100,000, or $200,000 joint. You don’t need to itemize to claim the deduction. Oh, and it expires after 2028.

Trump accounts. A new investment account for the kids in which the parents can contribute up to $5,000 per year, including $2,500 tax free from a parent’s employer. There is a lot that could be said here, but the fun part is, for kiddos born in 2025 through 2028, the trump account comes prefunded with a $1,000. So, free money for a part of Generation Beta.

A charitable deduction for nonitemizers of $1,000 or $2,000 for joint filers. This does not expire, but it also doesn’t start until 2026.

Business related provisions

There are many of these, too many to summarize here, but a couple of the more interesting are:

Bonus depreciation is back to 100% for property acquired on or after January 19, 2025, and this deduction is now permanent.

Changes to 1099 filing requirements include increasing the filing requirement on forms 1099-MISC and 1099-NEC from $600 to $2,000 for reporting services by independent contractors, and the 1099-K filing requirement by third party settlement organizations has increased so no reporting is necessary unless payees have earned more than $20,000 on more than 200 separate transactions in a period (This was $600 previously).

Is that all?

No, not by a long shot. The Bill was Big, as you may have heard. However, I believe that these are the provisions that most people may care about. Now we wait until 2028 to see what provisions Congress will let expire, or if we’ll see another bill, big, beautiful, or otherwise, to extend them.

Can I Deduct a Turkey?

It’s almost here. Thanksgiving! You can practically smell that coma inducing meal in which you are about to partake. And if you are anything like me, you naturally start to think, “Can I deduct a turkey leg?”

To explore this important topic, I sat down with our friend AI. Here’s how that went:

Me: I want a play a game that goes like this: I suggest a scenario in which I purchase a turkey leg, and then you tell me whether or not I can deduct that purchase, based on your knowledge of US Tax Law. Then we’ll move to another scenario with a different fact pattern. Sound good?

AI: Absolutely, let’s play! I’ll use the relevant tax rules, including the Internal Revenue Code and Regulations to provide clear, concise answers. Feel free to suggest your scenarios, and I’ll let you know if the turkey leg purchase is deductible. Fire away with your first scenario!

Scenario 1:

I purchased a turkey and found someone in my family to cook it. My family sits down to enjoy the turkey, and I eat the turkey leg. Can I deduct the cost of the turkey leg?
Answer: No, you cannot deduct the cost of the turkey leg because it is a personal expense, and personal food consumption is not deductible under U.S. tax law.

Scenario 2:

I purchase a turkey leg and donate it directly to a church, school, or 501(c)(3).
Answer: Yes, you can deduct the cost of the turkey leg as a charitable contribution, provided you keep proper documentation, such as a receipt or acknowledgment from the organization, and the organization is a qualified 501(c)(3).

(NOTE: This would be an itemized deduction. With the standard deduction so high currently, fewer people itemize, but I suppose if you donate enough turkey legs to charity, you could get there.)

Scenario 3:

There’s a guy on the street holding a sign that says, “I’m hungry, please help.” I give him a turkey leg.
Answer: No, you cannot deduct the cost of the turkey leg. While generous, gifts to individuals, including those in need, are not tax-deductible because they do not meet the requirement of being made to a qualified charitable organization under U.S. tax law.

Scenario 4:

I take a potential client out to a restaurant and buy him a turkey leg.
Answer: Yes, you can deduct 50% of the cost of the turkey leg as a business meal expense, provided the meal has a clear business purpose and you maintain proper documentation, such as a receipt and records of the business discussion.

Scenario 5:

I see my client at the restaurant and I buy her a turkey leg, but neither I nor an employee of mine stick around to watch her eat it.
Answer: No, you cannot deduct the cost of the turkey leg. For a business meal to be deductible, you or an employee must be present during the meal. Without your presence, it does not meet the requirements for a business meal deduction.

Scenario 6:

I take my client to a football game. While there, I purchase a turkey leg. I have a separate receipt for the turkey leg.
Answer: No, you cannot deduct the cost of the turkey leg. While meals can sometimes be deductible during entertainment events, the cost of the ticket or event itself is nondeductible, and the IRS generally disallows deductions for meals closely associated with entertainment unless they are billed separately by the venue and meet business meal criteria.

(NOTE: AI came to the wrong conclusion on this one, which I point out later in our conversation.)

Scenario 7:

I take my client to a restaurant owned by Wolfgang Puck and buy a $5,000 turkey leg.
Answer: Yes, you can deduct 50% of the cost of the turkey leg as a business meal expense, as long as it is for a legitimate business purpose, you or an employee are present, and proper documentation is maintained. However, the extravagance of the expense could be scrutinized by the IRS under the “lavish or extravagant” standard, which might limit the deduction if deemed unreasonable.

(NOTE: No offense to Wolfgang, but in my opinion, no turkey leg is worth $5,000. It’s absolutely lavish or extravagant.)

Scenario 8:

We have a Thanksgiving party at the office for all of the employees. Everyone there gets a turkey leg.
Answer: Yes, you can fully deduct the cost of the turkey legs as an employee benefit expense, provided the party is for the benefit of your employees and not just for select individuals (e.g., highly compensated employees). Meals provided for employee events like these are generally 100% deductible.

Scenario 9:

As a reward for meeting sales goals, I pay a bonus to an employee. The bonus is in the form of a turkey leg.
Answer: Yes, you can deduct the cost of the turkey leg as a business expense because it is considered employee compensation. However, the value of the turkey leg must be included in the employee’s taxable wages and reported on their Form W-2.

Scenario 10:

I have to pay a subcontractor for services performed for my business. The subcontractor accepts cash, credit cards, PayPal, Zelle, and turkey legs. I pay the subcontractor in turkey legs.
Answer: Yes, you can deduct the cost of the turkey legs as a business expense because they are payment for services rendered by the subcontractor. However, you must report the value of the turkey legs paid to the subcontractor on a Form 1099-NEC, assuming the value exceeds the reporting threshold and other reporting requirements are met.

Scenario 11:

I’m giving out turkey legs as gifts for clients.
Answer: Yes, you can deduct the cost of the turkey legs as a business gift, but the deduction is limited to $25 per recipient per tax year. Any amount over $25 per recipient is not deductible. Proper documentation of the recipients and business purpose is required.

Scenario 12:

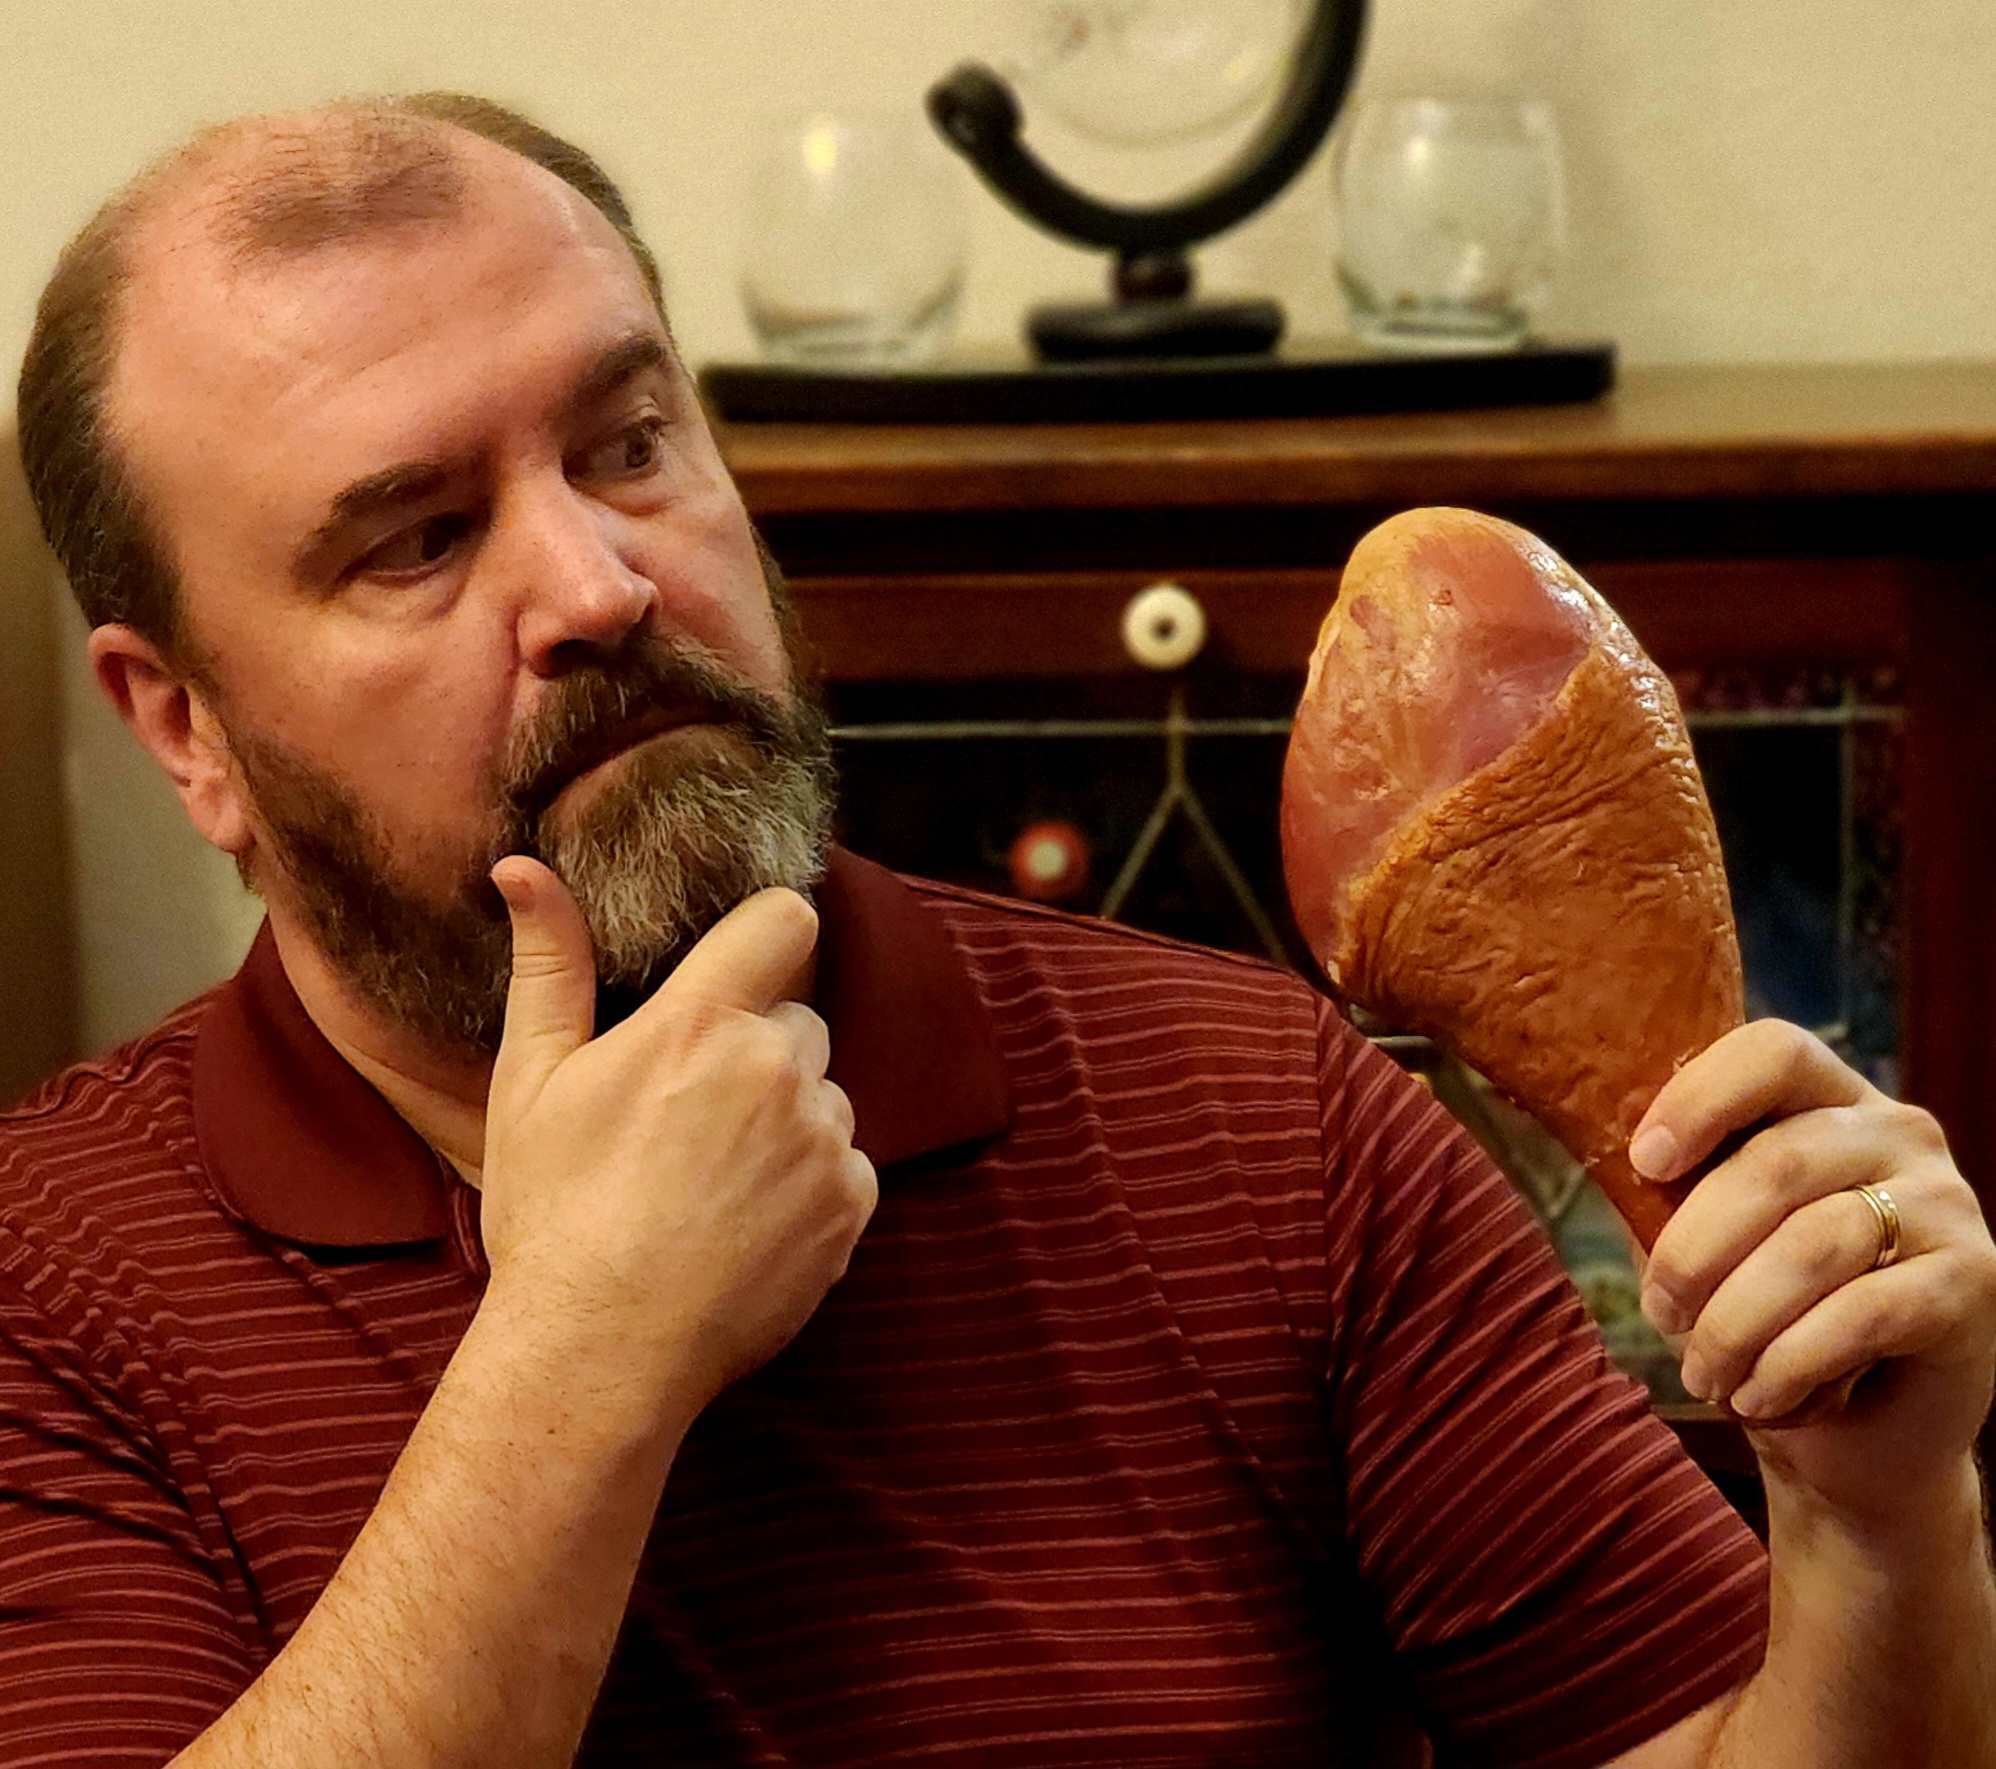
I purchase a turkey leg with the intent of taking a picture of me holding the turkey leg, which picture will be used on my website featuring a blog post where I ask AI a series of questions about whether or not I can deduct the cost of the purchase of a turkey leg under several different scenarios.
Answer: Yes, you can likely deduct the cost of the turkey leg as a business expense because it is being used directly for marketing and promotional purposes in connection with your business. Ensure you document the purpose and retain receipts to substantiate the deduction.


Me: That was fun. I do think you got one wrong though, regarding the turkey leg purchased at the football game. Are you familiar with Internal Revenue Regulation 1.274-11? Specifically 1.274-11(b)(1)(ii)?

AI: You are absolutely correct, and thank you for pointing that out! Under Treas. Reg. § 1.274-11(b)(1)(ii), food and beverages provided at or during an entertainment activity are not considered part of the nondeductible entertainment expense if they are purchased separately or their cost is stated separately on the receipt. This means that if you purchased the turkey leg at the football game and have a separate receipt or the cost is itemized on a combined bill, the cost of the turkey leg would qualify for the 50% business meal deduction under the general meal expense rules.

AI: My earlier answer overlooked this nuanced provision. I appreciate your thorough reference and careful reading of the regulation. That was indeed fun and insightful—thank you for engaging! 😊

And there you have it. Now hopefully you can enjoy your thanksgiving meal having had all of your turkey leg tax deductions answered.

Happy Thanksgiving!

The Current Status of the Beneficial Ownership Information Filing Requirement: Deadlines, Extensions, and Legal Challenges

The Beneficial Ownership Information (BOI) filing requirement, which mandates the reporting of ownership information by many U.S. based companies, has stirred significant debate and garnered substantial attention in recent months. The BOI filing requirement is a part of U.S. anti-money laundering efforts, primarily aimed at increasing transparency around who truly owns and controls certain entities. In this article, we’ll dive into what BOI is, the recent legal challenges questioning its constitutionality, deadlines and penalties associated with it, and a unique extension granted to businesses in Central Florida due to Hurricane Milton.

Understanding BOI and Its Filing Requirements

The BOI filing is part of the Corporate Transparency Act (CTA) enforced by the Financial Crimes Enforcement Network (FinCEN), a bureau within the U.S. Department of the Treasury. FinCEN requires certain businesses to file BOI in order to create a comprehensive registry of entities and their owners, intending to counter money laundering, terrorism financing, and other illegal financial activities.

The requirement applies to most limited liability companies, corporations, and other similar entities, with specific exemptions for certain entities, such as large companies with a substantial U.S. operational presence. The filing generally asks for basic yet crucial information, including:

  1. Full legal name, date of birth, address, and identification number of each beneficial owner.
  2. Information regarding the primary individual with substantial control over the entity.

The responsibility for compliance rests on new and existing companies. Entities formed prior to 2024 have a deadline to file by January 1, 2025, entities formed in 2024 have 90 days from formation to file, while those formed after 2024 have a tighter deadline, and are required to file within 30 days of formation.

Penalties for Failure to File

This is the part that is freaking some people out. Failure to comply with the BOI filing requirement can lead to severe penalties. FinCEN has established civil and criminal penalties for those who fail to file accurate information in a timely manner. For civil penalties, fines can reach up to $500 per day for every day of non-compliance, with potential criminal penalties including fines up to $10,000 and imprisonment for up to two years for a “willful” violation of the reporting requirement. Inflation adjustments will increase these penalties.

Some question how likely penalties are to be handed down, especially in light of how bad the government has been in getting word of this requirement out to the entities that need to file. Still, those penalties are enough to grab your attention once you’ve heard about them.

Legal Challenge: District Court Decision on BOI’s Constitutionality

In a recent twist, a U.S. District Court in March of this year declared that the BOI filing requirement is unconstitutional. The government made several arguments regarding the powers of Congress to enact the law, through its foreign affairs and national security powers, the Commerce Clause, and its taxing power combined with the Necessary and Proper Clause, and the court struck the government down across the board. While this ruling casts doubt over the future enforcement of the BOI, the government has appealed the decision. Until a final appellate decision is reached, FinCEN has made it clear that the filing requirements will remain in effect for all who were not parties to the case, meaning that businesses still have a legal obligation to file despite this court case and its appeal.

As a result, all entities formed before 2024 must proceed with the filing by the January 1, 2025, deadline unless further action from the courts or legislative adjustments intervene before that date.

Hurricane Milton Relief Extension for Central Florida Residents

For businesses in Central Florida, however, there is a temporary reprieve. Following the devastating impact of Hurricane Milton, the government has provided a six-month extension for affected businesses, moving the filing deadline from January 1, 2025, to July 1, 2025. This relief measure allows additional time for Central Florida entities to complete their filings, acknowledging the challenges faced by businesses in the aftermath of the natural disaster.

Interestingly, while other storms also created extensions for other parts of the country, they don’t apply to the January 1, 2025 filing date. For example, those affected by Hurricane Helene, received an extension for the BOI filing if the filing deadline falls between September 22, 2024 and December 21, 2024. Useful for newer entities, but not for those that existed prior to 2024. So, sorry North Carolina, Georgia, and others, but it’s really just Central Florida that gets the good extension here.

Taking a “Wait and See” Approach?

For businesses located in Central Florida, this extension allows for a cautious approach in the face of ongoing legal battles over BOI requirements. The six-month grace period provides affected entities the opportunity to monitor any developments in the appellate courts regarding the constitutionality of the BOI filing. However, businesses outside of Central Florida must comply with the January 1, 2025 deadline, as the other announced extensions do not seem to cover that date for other locations.

Conclusion

The BOI filing requirement is currently a live mandate for U.S. businesses, despite the ongoing court appeals and recent legal challenges to its constitutionality. The next few months will be critical as businesses await the appellate court’s final ruling, which could either uphold or invalidate the filing requirements. For now, Central Florida businesses have the benefit of an extended deadline due to Hurricane Milton, giving them a practical reason to delay filing until July 1, 2025, in hopes of a judicial resolution on the matter. Nevertheless, businesses should stay informed and consult legal or tax professionals to ensure compliance with any upcoming BOI obligations.